


After twelve years of digging through file cabinets and cross-referencing medical records with property damage estimates, I have learned one thing that most people don’t realize until it is too late: Insurance companies view your car and your body as two entirely different business lines.
Most folks think a car accident is one big, singular event. To an insurance adjuster, however, it is a “split claim.” The property damage (the metal) moves fast. The bodily injury (the you) moves slow. If you don’t treat them as separate projects with their own documentation, you risk leaving money on the table or, worse, losing your right to compensation entirely.
Phase 1: The First 30 Minutes (Don’t Skip This)
I’ve seen cases tank because a client was too “polite” at the scene. They apologized, said they were “fine,” and skipped calling the cops. Do not do this. Your documentation starts the moment the airbags deploy.
Safety and Scene Documentation
First, get to a safe spot. If the vehicles are drivable, move them to the shoulder. If you are in a high-traffic area, use an app like Google Maps (e.g., this example of a major intersection) to pinpoint your exact location coordinates. If the police ask where the impact occurred, “near the light” isn’t good enough—pinning it helps us What Should I Do If Someone Posted False Scam Allegations? prove traffic patterns or sight-line issues later.
What to document:
- Vehicle positions: Photos of where the cars ended up.
- The “Other” Guy: A photo of their insurance card and driver’s license.
- Witnesses: Get a name and phone number. If they leave before the cops arrive, you lose that neutral perspective.
The Police Report is Your North Star
In Texas, if there is over $1,000 in damage or an injury, you need a police report. If the officer says they aren’t coming to the scene, you must file a “Blue Form” (CR-2) with the Texas Department of Transportation. Why? Because insurance adjusters are trained to doubt your story. An official report acts as a shield against their claims that you are “at fault” or “exaggerating.”
The Golden Rule: Keep Your Documentation Separate
When you start calling insurance companies, stop trying to fix your car and your back in the same sentence. When you are uploading receipts to an insurer’s online portal—often guarded by a What is the Safest Way to Ask Customers for Reviews on Google? to ensure you are a real human and not a bot—make sure you are filing them into the correct digital folder. Mixing up repair invoices with your MRI scans is a recipe for a clerical disaster.
Property Damage vs. Medical Records: A Quick Comparison
Why “It’s Probably Fine” is a Dangerous Phrase
I have heard it a thousand times: “My back hurts, but I’ll wait to see if it goes away.”
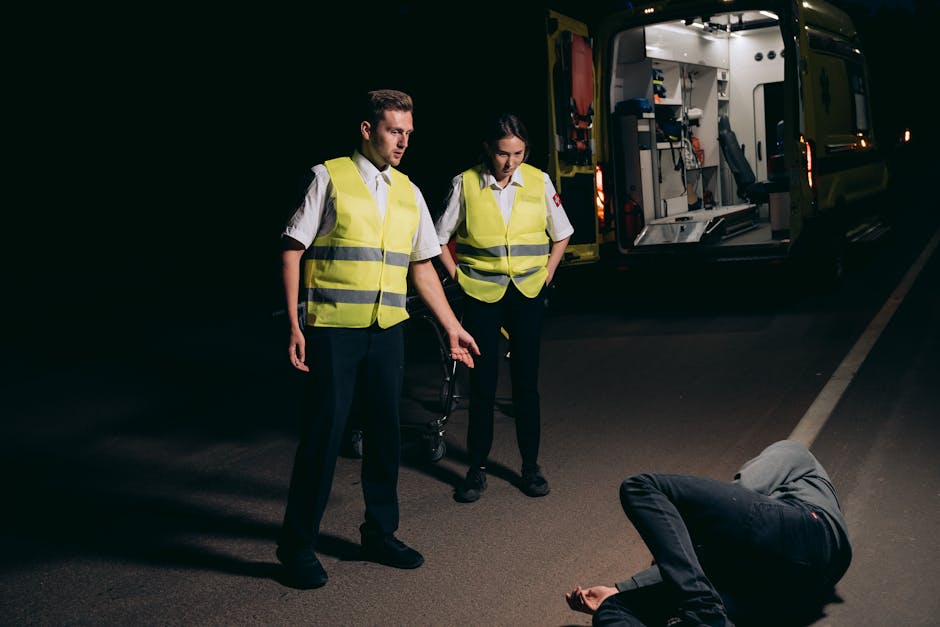
Do not do this. If you don’t seek medical attention within 72 hours of a crash, the insurance company will argue that your injuries were caused by something else—like sleeping wrong or a trip to the gym. They will use your medical records against you to show a “gap in treatment.” If you go to the ER or an urgent care, you start a paper trail. If you wait, you have no proof.
What to Say and What Not to Say
When the adjuster calls—and they *will* call—you need to be disciplined. They aren’t trying to help; they are trying to limit their payout.
What to say:
- “I am still undergoing medical evaluation and cannot discuss the extent of my injuries.”
- “I have submitted the police report and scene photos to your online portal.”
- “Please send all settlement offers regarding my vehicle repair in writing.”
What NOT to say:
- “I’m feeling much better today.” (The adjuster will use this to cut off your medical coverage.)
- “I think it might have been my fault.” (Never speculate on liability.)
- “I’m just happy to get this over with.” (This gives them leverage to lowball you.)
Insurance Coverage Review: Read the Fine Print
Before you talk numbers, pull out your own Declarations Page. You need to know what you are actually covered for. Does your policy have Personal Injury Protection (PIP)? Does the other driver have enough liability insurance to cover both the car *and* your medical bills? If they don’t, you need to check if you have Underinsured Motorist (UIM) coverage.
When you review these, look for the following:
Final Thoughts: The Paralegal’s Perspective
If there is one thing you take away from this, let it be this: Trust your documents, not the adjuster. The adjuster’s job is to protect their company’s bottom line. Your job is to document your reality.
Always keep a physical file of every receipt, every medical bill, and every letter sent to you. If you are ever at a crossroads, look at the timeline. Did you see the doctor? Did you report the damage? If the documentation isn’t there, as far as the law is concerned, the event didn’t happen. Stay organized, stay cautious, and don’t rush the process just because the insurance company makes it sound like they are doing you a favor.
Disclaimer: I am a legal writer, not an attorney. This information is for educational purposes based on my experience in the field. Always consult with a licensed attorney in your jurisdiction for specific legal advice regarding your crash.
